
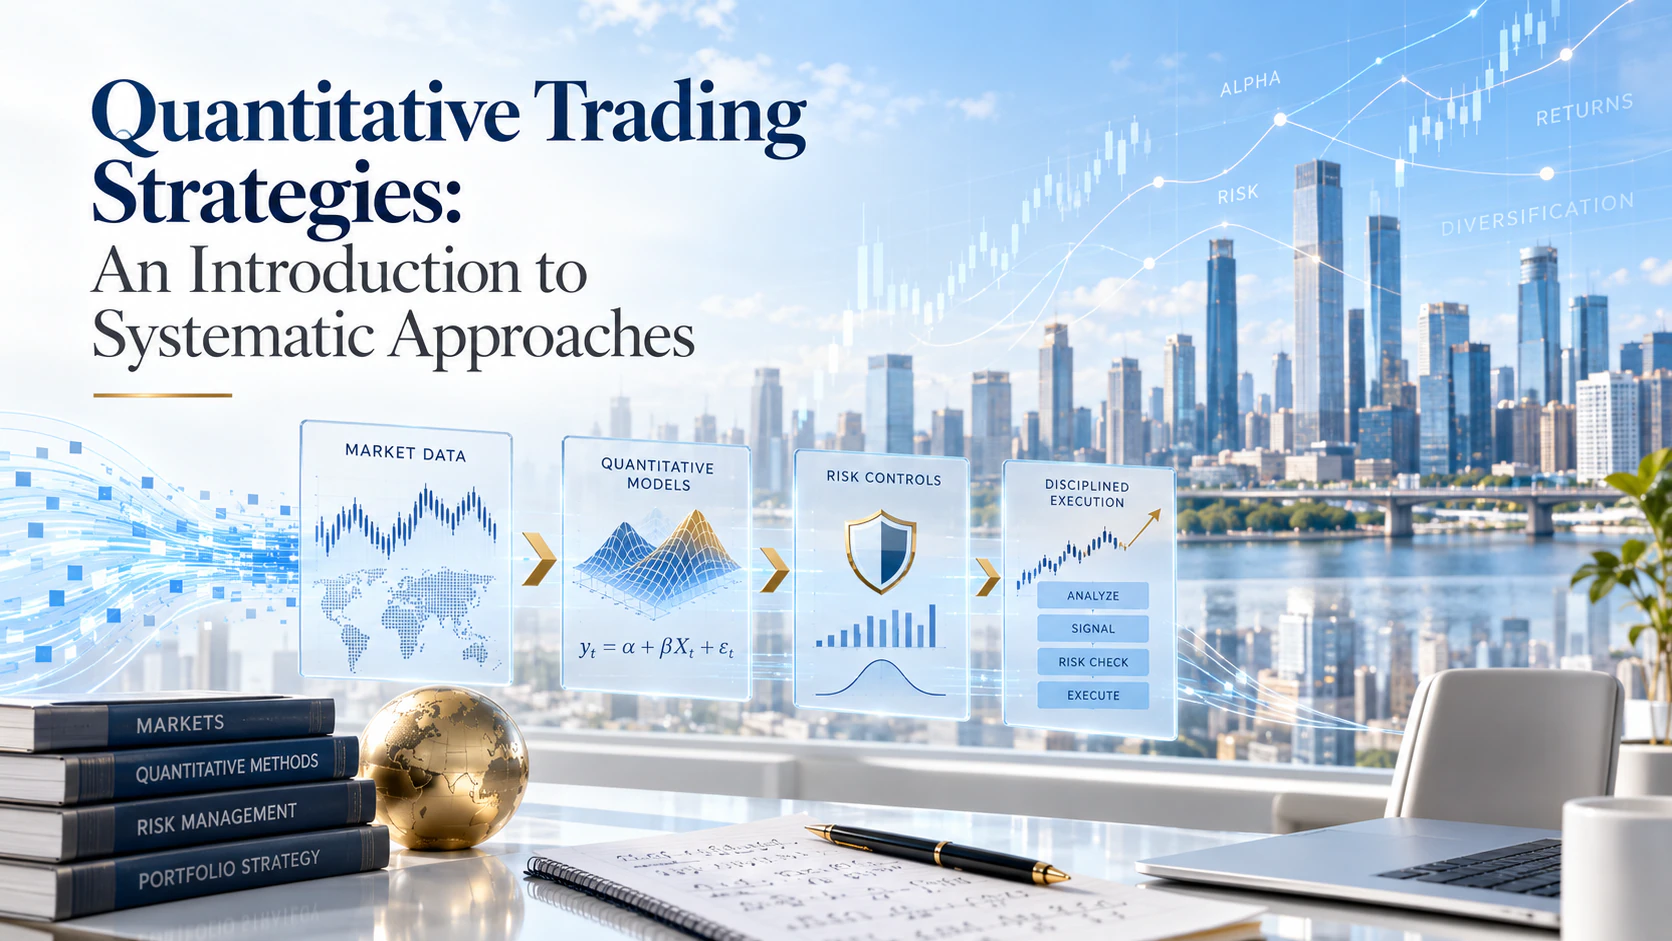
Financial markets are shaped by information, expectations, liquidity, human behavior, and unexpected events. Because these forces interact continuously, trading decisions based entirely on intuition can become inconsistent. Quantitative trading offers a more systematic alternative by translating investment ideas into measurable rules that can be tested, monitored, and executed repeatedly.
Quantitative trading uses mathematical models, statistical analysis, and computer programs to identify potential opportunities in financial markets. Its purpose is not to predict every price movement correctly. Instead, it seeks to find repeatable patterns, manage uncertainty, and apply the same decision framework across many trades.
## From an Investment Idea to a Trading Rule
Every quantitative strategy begins with a hypothesis about market behavior. A researcher might believe that established price trends tend to persist, that extreme short-term movements are likely to reverse, or that the prices of related assets may temporarily diverge before converging again.
A hypothesis becomes useful only when it can be expressed as a clear set of rules. The system must define which instruments it can trade, what conditions create an entry signal, when a position should be reduced or closed, and how much capital may be committed.
This structure separates systematic trading from discretionary decision-making. Rather than changing the strategy in response to fear or excitement, the trader follows predefined conditions. Human judgment remains important, but it is primarily applied to research, model governance, risk limits, and exceptional situations.
## Data as the Foundation
A quantitative model is only as reliable as the data behind it. Common inputs include prices, trading volume, volatility, interest rates, corporate fundamentals, economic indicators, and order-book information. Some strategies also use alternative sources such as news sentiment, supply-chain activity, web traffic, or satellite observations.
More data does not automatically produce a better strategy. Missing observations, inaccurate records, inconsistent timestamps, and changes in market structure can distort the results. Survivorship bias can also create an unrealistic picture when a dataset includes only assets that remain active today while excluding those that failed or were delisted.
For this reason, data preparation is not a minor technical step. It is a central part of quantitative research. Researchers must understand where the information came from, when it became available, and whether the model could realistically have used it at the time of each historical decision.
## Common Quantitative Trading Strategies
Trend-following strategies attempt to benefit from price movements that continue in the same direction. They may use moving averages, breakouts, or other measures to determine whether an upward or downward trend has become sufficiently strong.
Momentum strategies rank assets according to their recent performance. The model may buy stronger assets, avoid weaker ones, or combine long and short positions. Although momentum and trend following are related, momentum strategies often emphasize relative performance across a group of securities.
Mean-reversion strategies are built on the idea that certain price movements become temporarily excessive. When an asset moves unusually far from a statistical reference point, the strategy may take a position that benefits if the price returns toward its typical range.
Statistical arbitrage looks for relative pricing relationships among securities. Pairs trading is a familiar example: if two historically related assets diverge, the strategy may buy the relative underperformer and sell the outperformer. The opportunity depends on the relationship converging, not necessarily on the direction of the overall market.
Factor-based strategies construct portfolios using characteristics such as value, quality, size, low volatility, or momentum. Instead of depending on a single trade, they distribute exposure across a larger portfolio designed to capture a particular return pattern.
## Backtesting and the Danger of Overfitting
After a strategy has been defined, it is usually evaluated with historical data. A backtest estimates how the rules might have performed if they had been applied in the past. Researchers examine returns alongside risk measures such as volatility, maximum drawdown, the Sharpe ratio, and the consistency of performance across different periods.
A strong historical result does not guarantee that a strategy will succeed in live markets. If researchers repeatedly change parameters until the model fits historical data perfectly, they may create a system that explains noise rather than a persistent relationship. This problem is known as overfitting.
To reduce this risk, researchers divide data into separate development and evaluation periods. Out-of-sample testing, walk-forward analysis, and stress testing can show whether the strategy remains credible beyond the conditions used to create it. Testing across different assets and market regimes can also reveal whether the apparent advantage is stable or dependent on one favorable period.
## Realistic Costs and Execution
A theoretical signal is not the same as an executable trade. Commissions, bid-ask spreads, slippage, financing expenses, and market impact can substantially reduce returns. These costs are especially important for high-frequency strategies or strategies that trade less-liquid instruments.
Market capacity also matters. A strategy that performs well with a small amount of capital may become less effective as its position size increases. Large orders can move prices, reveal trading intentions, or take longer to complete.
A realistic model therefore needs to simulate how trades could actually be executed. It should account for order timing, available liquidity, partial fills, and the possibility that the observed market price will no longer be available when an order reaches the exchange.
## Risk Management and Continuous Oversight
Risk management is not a separate addition to a quantitative strategy; it is part of the strategy itself. A complete system defines position sizes, portfolio concentration limits, leverage restrictions, loss thresholds, and rules for reducing exposure during abnormal conditions.
Diversification can help limit dependence on a single asset, signal, or market environment. However, correlations often rise during periods of stress, so risks that appear separate under normal conditions may suddenly become connected.
Live monitoring is equally important. Market behavior changes, competitors adapt, and previously reliable relationships can weaken. The system should compare actual results with expected behavior, detect data or execution failures, and trigger review when performance moves outside established limits.
Artificial intelligence can expand this process by analyzing complex information and identifying nonlinear relationships. Yet greater model complexity also introduces challenges involving explainability, stability, and governance. Discussions shared through the [KAEL AI Facebook page](https://www.facebook.com/profile.php?id=61594050729769) can help readers follow how systematic finance and AI-assisted decision systems continue to evolve.
The objective of quantitative trading is not to discover a formula that is always correct. It is to create a disciplined process for forming hypotheses, testing them honestly, controlling risk, and adapting when evidence changes. Sustainable performance is more likely to come from reliable data, realistic assumptions, robust execution, and consistent research discipline than from any single indicator or model.