
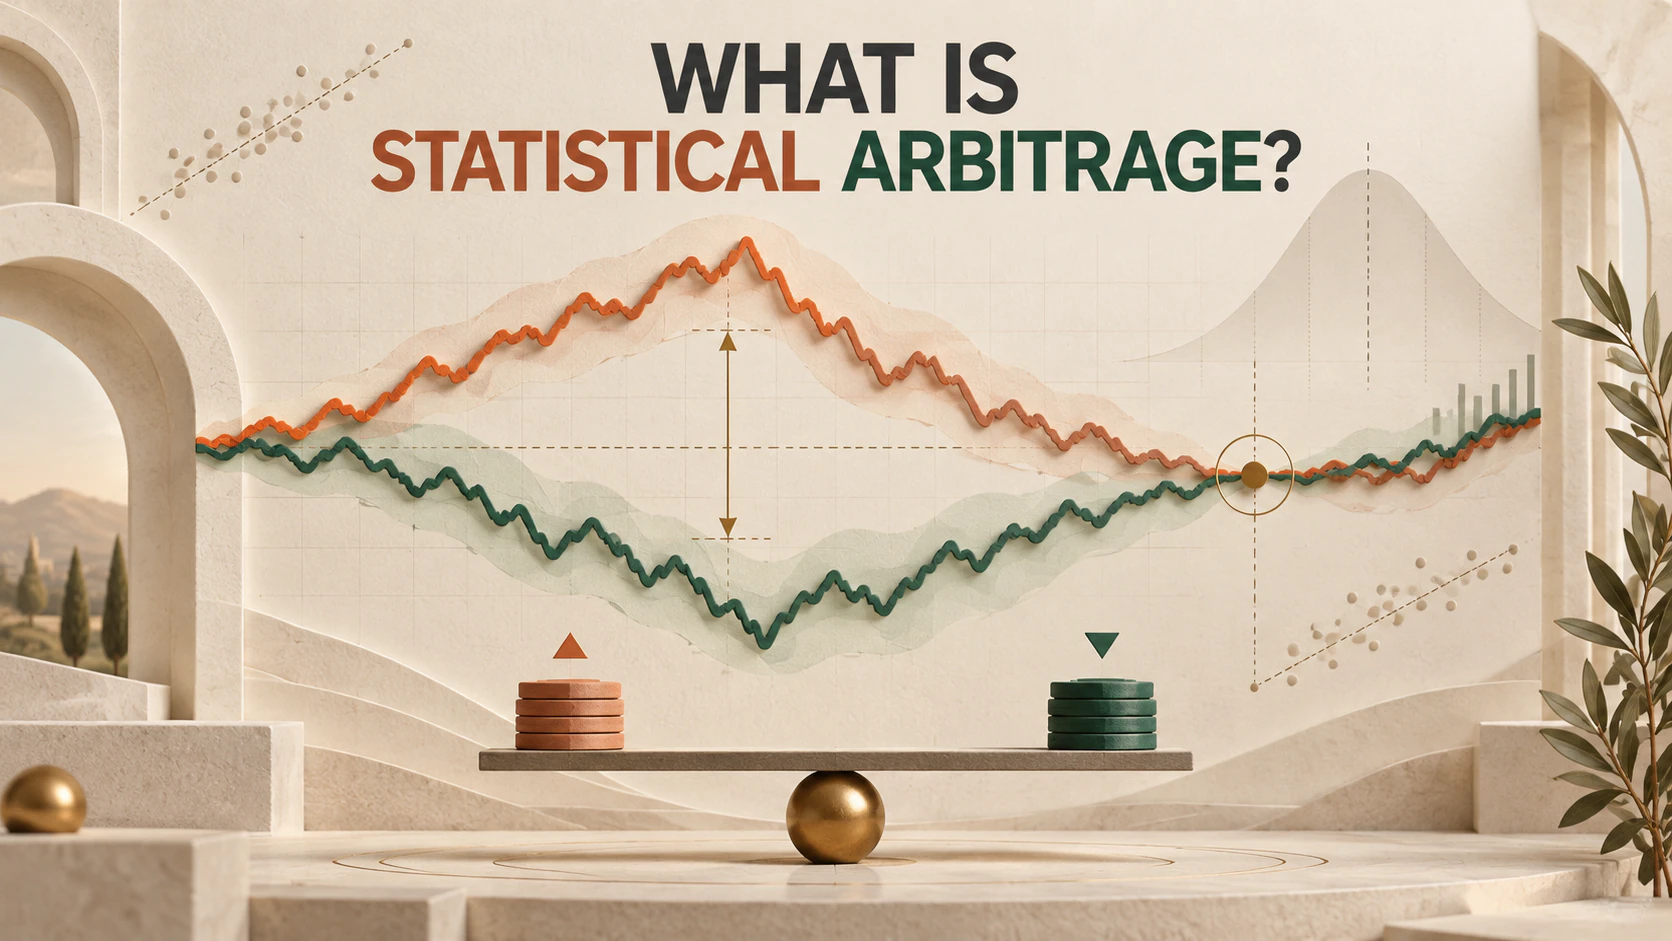
Statistical arbitrage, often shortened to Stat Arb, is a quantitative trading approach that uses data and statistical models to identify temporary pricing differences among related securities. A strategy typically buys assets considered relatively undervalued and sells short those considered relatively overvalued, aiming to profit if their prices return to a more normal relationship.
Despite its name, statistical arbitrage is not the same as risk-free arbitrage. Traditional arbitrage attempts to capture a clearly observable price difference for the same or equivalent asset in separate markets. Statistical arbitrage relies on probabilities. A relationship that appeared reliable in historical data may weaken, change or disappear, making losses possible even when a model has performed well in the past.
## How Does Statistical Arbitrage Work?
A statistical arbitrage system begins by analyzing market data. This may include prices, returns, trading volume, volatility, sector classifications and other variables that could explain how securities move in relation to one another.
Many strategies are based on mean reversion—the idea that an unusually wide deviation from a historical relationship may eventually move back toward its average. Suppose the shares of two companies in the same industry have generally displayed a stable relative-price relationship. If one stock suddenly rises while the other falls behind, a model may identify the divergence as a possible trading opportunity.
The strategy could buy the relatively weaker stock and sell short the relatively stronger one. If the difference narrows, the combined position may generate a profit. The objective is not necessarily to predict whether the entire market will rise or fall. Instead, it is to capture the relative movement between the two positions.
This long-short structure may reduce broad market exposure, but it does not eliminate risk. Both positions can move against the strategy, and the expected convergence may take longer than anticipated or never occur.
## Pairs Trading and Portfolio-Based Strategies
Pairs trading is one of the simplest forms of statistical arbitrage. Two securities may be selected because they operate in similar industries, respond to common economic forces or exhibit a measurable statistical relationship.
Correlation is sometimes used during the selection process, but high correlation alone does not establish a stable long-term connection. More rigorous approaches may use cointegration analysis, distance measures, time-series models or other statistical techniques to determine whether a price relationship is sufficiently persistent.
Institutional statistical arbitrage strategies frequently extend beyond individual pairs. A portfolio may contain dozens or hundreds of long and short positions. The system can rank securities according to their relative attractiveness, buy those with higher scores and short those with lower scores.
Positions are then adjusted to limit unintended exposure to the market, industries, regions, company size, volatility and investment-style factors. This creates a diversified framework in which the performance of one security should have less influence on the overall result.
## The Statistical Arbitrage Process
The first stage is defining the investment universe. A strategy may focus on stocks, ETFs, futures, currencies or other liquid instruments. Securities with unreliable data, insufficient trading activity or limited short-selling availability may be excluded.
The next stage is data preparation and model development. Market datasets often contain missing observations, abnormal prices, corporate actions and timing inconsistencies. These issues must be corrected before researchers test potential signals.
Once a model has been developed, it produces scores or trading signals. These signals estimate which assets appear relatively attractive and which appear relatively expensive. A signal does not automatically become a trade. Its expected advantage must be large enough to justify transaction costs and the associated risk.
Portfolio construction determines the size of each position while controlling market and factor exposures. Risk limits may restrict leverage, sector concentration, individual security exposure and the total amount that can be traded without significantly affecting market prices.
Finally, an execution system places and monitors orders. Positions may be closed when the relationship converges, the signal reverses, a time limit expires or a risk threshold is reached. Models and portfolios must be monitored continuously because market conditions can change rapidly.
## Why Is Automation Important?
Statistical arbitrage often targets small pricing effects across a large number of securities. Opportunities may appear and disappear quickly, making continuous manual analysis impractical.
Automated systems can process data, calculate signals, optimize portfolios and execute orders more consistently. However, automation also allows errors to spread faster. Incorrect data, faulty assumptions or execution problems can create many undesirable positions within a short period.
Effective systems therefore require validation checks, position limits, real-time monitoring and emergency controls. Human oversight remains important, especially when markets behave outside the conditions represented in the model.
## Major Risks
Model risk is one of the most important concerns. A pattern discovered in historical data may be coincidental or overly fitted to a particular sample. A model that performs impressively in a backtest may fail when exposed to new data.
Relationships can also break because of mergers, defaults, regulatory decisions, technological disruption or changes in company fundamentals. In such cases, a price divergence may reflect a genuine structural change rather than a temporary mispricing.
Trading costs present another challenge. Statistical arbitrage strategies can have high turnover, so commissions, bid-ask spreads, slippage, borrowing fees and market impact may consume much of the theoretical return.
Leverage and funding risk can turn temporary losses into forced liquidation. A forecast may eventually prove correct, yet the strategy might be unable to maintain its positions through margin calls or prolonged adverse movements.
Crowded positioning is also dangerous. When many funds use similar signals and risk models, they may hold comparable positions. If one participant must unwind rapidly, falling prices can trigger losses and additional selling across other portfolios.
## Evaluating a Strategy
Historical return alone is not enough to assess a statistical arbitrage strategy. Researchers should examine drawdowns, volatility, risk-adjusted returns, turnover, transaction costs, trading capacity and performance across different market environments.
Backtests should address look-ahead bias, survivorship bias and overfitting. Out-of-sample testing, rolling validation and stress scenarios can provide a more realistic picture of how a model may behave. Tests should also consider reduced liquidity, delayed execution, rising borrowing costs and sudden changes in correlations.
Statistical arbitrage demonstrates how data, mathematical models and automated execution can be combined to search for relative-value opportunities. Its strength lies in applying small statistical advantages systematically across a diversified portfolio. Its limitation is equally important: statistical relationships express probabilities, not guarantees. Sustainable implementation depends on robust research, realistic cost assumptions, disciplined risk management and continuous adaptation to changing markets.